The Strongest Argument Against SpaceX’s Compute Pricing Is SpaceX
Programming note: Every MBI Deep Dives article, including the entire archive of 630 posts, now comes with audio. To listen, just open the article on the website and hit play on the player at the top. The audio lives on the website only, so it isn't included in the email, and it's available for only paying subscribers. Of course, Muse did this entire project for me over the last several days!
Even before SpaceX and Tesla’s potential merger, SpaceX already feels like an amalgamation of very different businesses with its three segments: Space, Connectivity, and Superintelligence or SI. I’ll stick with AI which is also my focus for today’s piece on SpaceX.
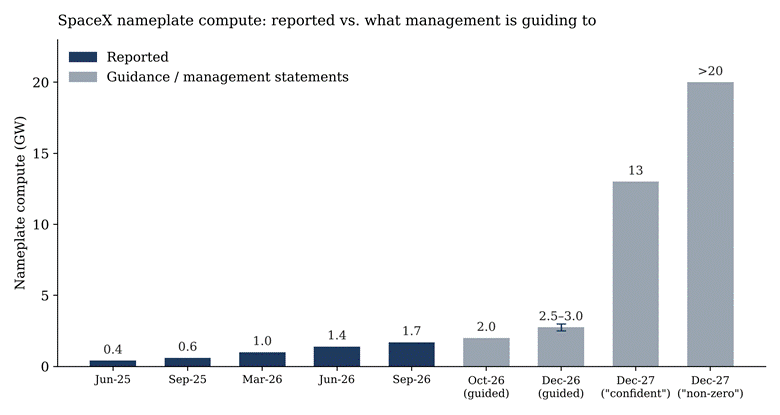
AI segment’s results were excellent! AI revenue was $7.6 billion, up from mere $0.8 billion a year ago, nameplate compute reached 1.7 GW at the end of September, and then Elon took the call somewhere else entirely: he is “highly confident” of adding an incremental 10 GW of compute in 2027, on top of the 2.5–3 GW SpaceX expects to have online by December; there is a “non-zero” chance of more than 20 GW; and all of this implies “Annual Recurring (!?) Revenue” of $500 billion to $1 trillion by the end of 2027. At least OpenAI and Anthropic have the decency to call ARR “Annualized Run Rate”. Not Elon Musk!
Predictably, much of the debate I have been noticing has been about supply: whether a company that wasn’t even a player in compute selling market a year ago can all on a sudden add 10 GW in twelve months. That’s certainly a relevant question, but there are also couple of more important questions than operational execution of bringing 10 GW incremental supply online.
I will elaborate these questions and my thoughts behind the paywall.
Subscribers get the daily journal and five+ years of Deep Dives, i.e. full-length analyses with financial models on 70+ companies. The daily is just how I think out loud between the Deep Dives!

 点赞
 收藏
 点踩
 分享