
French Bond Rout Puts Crisis at Heart of ECB Succession Endgame
 6


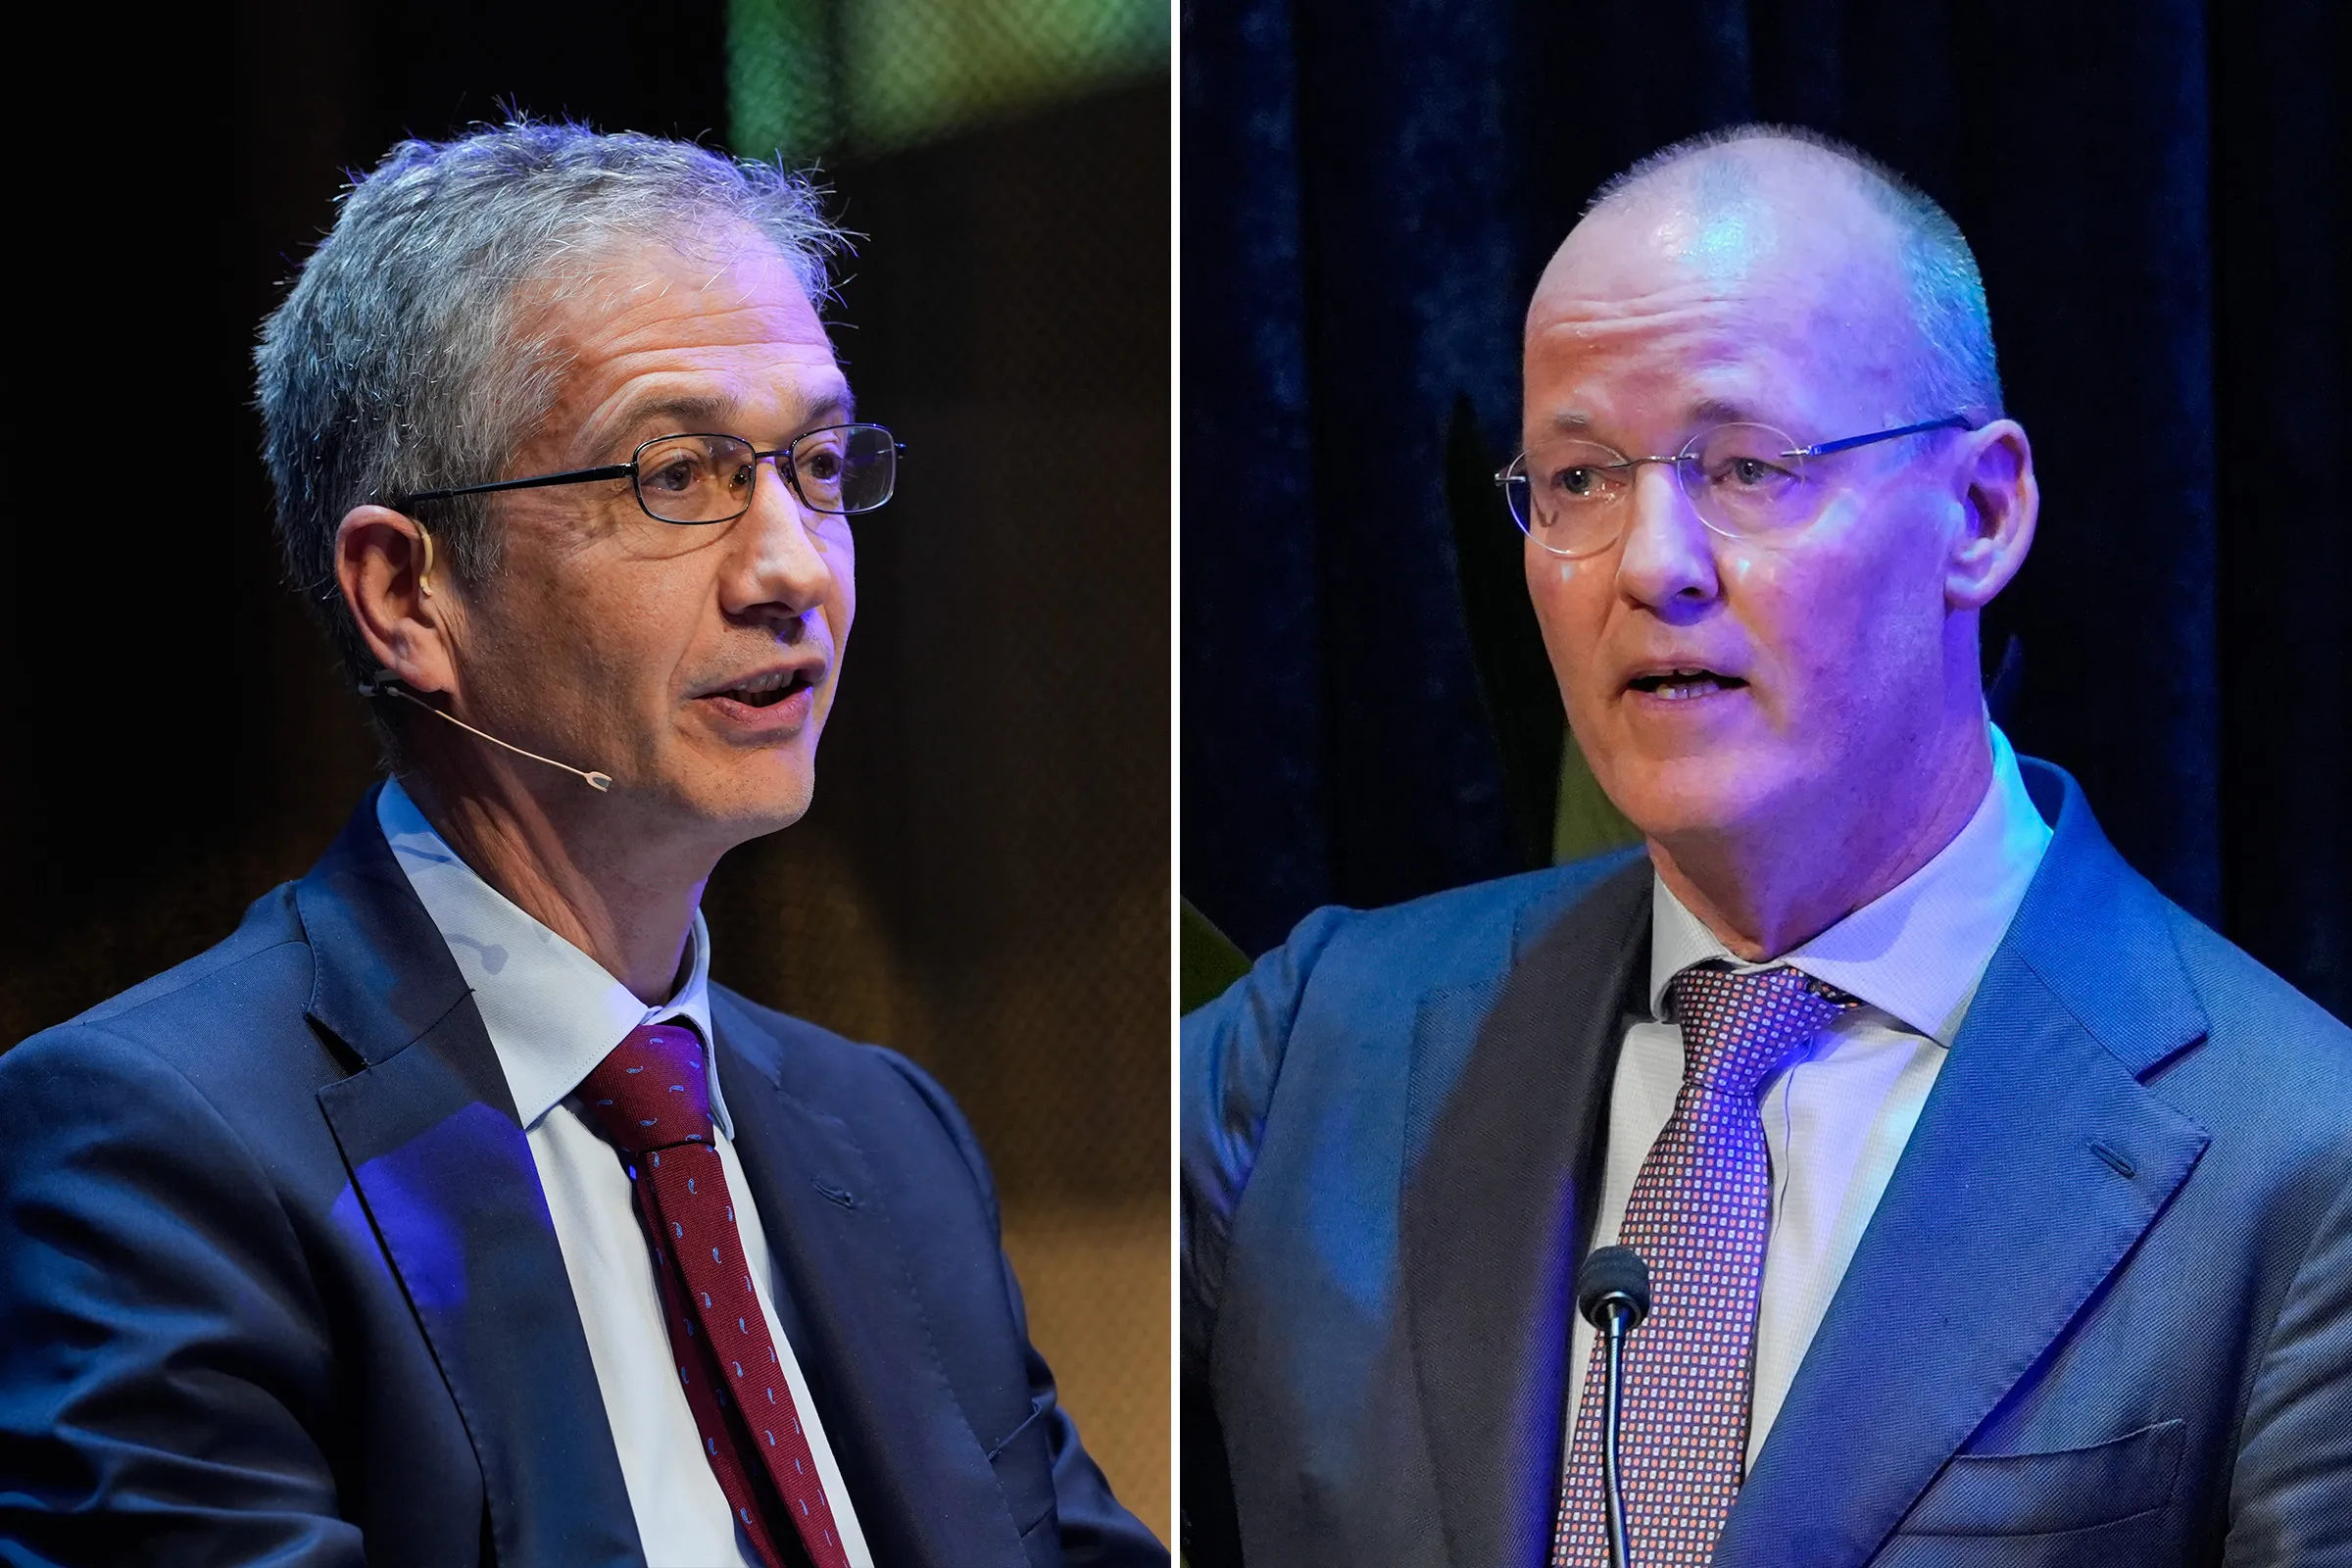
The European Central Bank’s presidency race looks increasingly likely to hinge on which candidate can best take on the bond vigilantes.
With France’s debt woes evoking memories of euro-zone turmoil and Christine Lagarde poised to quit, either Dutchman Klaas Knot or Spaniard Pablo Hernandez de Cos might soon find themselves in the hot seat amid financial turbulence.
Market tensions are an increasingly important factor in the next steps for the ECB, according to people familiar with policymakers’ discussions who declined to be identified because talks on the matter are private.
With that in mind, euro-zone insiders observe that the judgment of governments on candidates’ crisis-management skills is now dominating the choice on who should lead the ECB.
Since it’s hard to find much to contrast in the qualifications between the two candidates, assessing their credibility, authority and character in the face of turmoil has become even more important.
Such questions have long mattered more at the ECB because the asymmetry of a monetary union without fiscal conformity is such a vulnerability. Lagarde and two predecessors faced crises, and the worry of more trouble keeps haunting policymakers.
The problem now is that global scrutiny on public finances has combined with worries over high energy costs to ensnare France. Never has market speculation focused so ominously on such a large and pivotal member of the currency bloc.
With the government struggling to pass a budget, and riots in French cities showcasing the political challenge, government bond yields are signaling alarm bells that ultimately threaten to draw in the ECB as a firefighter.
“If there’s a meltdown in financial markets, then central banks have to intervene, but the question for any president is, how you do it, and how quickly?” said former ECB Chief Economist Peter Praet. “You need strict conditions, and you must avoid everything that risks fiscal dominance or weaken central-bank independence. This is particularly important right now.”
Lagarde has signaled she’ll leave early, but has yet to reveal when. The working assumption within euro-zone circles increasingly focuses on a departure in January.
That would make this week’s decision her penultimate one. “If it’s needed, we will come to a very quick solution on the board,” German Chancellor Friedrich Merz said on Monday. He met De Cos last week and Knot earlier this month, according to people familiar with the matter.
In one hint that what the Greek premier termed a “grand bargain” over the top job and two other ECB roles is in the works, euro-zone finance ministers extended a deadline for applications to replace outgoing German Executive Board member Isabel Schnabel to Nov. 27 from Oct. 28.
With bond-market tensions flaring up, the next president will need to face down investors speculating on ECB aid for France. Beyond that, the preferences of key nations in a future crisis fighter are no secret.
For the French, willingness to deploy any tool is key, with the memory of former ECB President Mario Draghi’s 2012 turmoil-calming pledge to do “whatever it takes” to save the euro a model of resolve. Budgetary hawks such as Germany, meanwhile, want a high bar for action.
The crisis test is arguably all the more valid since there’s not too much to distinguish the pedigree of Knot, the former head of the Dutch central bank, from those of De Cos, who runs the Bank for International Settlements.
“I don’t see any major ideological differences between the two,” said Emanuel Moench, co-director of the Frankfurt-based Centre for Central Banking, who’s worked at the US Federal Reserve and Germany’s Bundesbank. “Both are very experienced, both in monetary policy as well as and in financial stability issues.”
2011-2025: Dutch central bank, president2021-2025: Financial Stability Board, chair2009-2011: Dutch finance ministry, director of financial markets and deputy treasurer general1998-1999: International Monetary Fund, economist1995: University of Groningen, doctorate in economics
The two candidates are former members of the ECB’s Governing Council with doctorates and years of experience in setting euro-zone rates. Either the 59-year-old Knot or the 54-year-old De Cos would be its youngest chief so far, and each is regarded as a safe pair of hands.
Their similarities make this presidency race stand out as the first in euro history without a strong sense of divide over orthodoxy. Prior contests featured charged debates on which candidate might represent dogma or pragmatism.
Knot, a former head of the Financial Stability Board who led his central bank for 14 years, was known previously as a hawk, though he moderated that position during his tenure. Some memories of a strict northern-European stance during the Greek turmoil linger, but that was a long time ago.
He has been forthright in showcasing crisis skills. A paper this month for the Washington-based Peterson Institute for International Economics resembles a manifesto, explaining his journey from “skeptical to principled pragmatist.”
“I accepted each new instrument not out of enthusiasm for monetary activism, but out of recognition that allowing fragmentation to undermine monetary-policy transmission or fracture the singleness of money was incompatible with the ECB’s price-stability mandate,” Knot wrote on its latest crisis-fighting tool, the Transmission Protection Instrument.
2025-present: Bank for International Settlements, general manager 2018-2024: Bank of Spain, governor2019-2024: Basel Committee on Banking Supervision, chair2004-2007: ECB, adviser to Executive Board member José Manuel González-Páramo2004: Complutense University of Madrid, doctorate in economics
De Cos, who also chaired the Basel Committee on Banking Supervision, is reputed to be more dovish, albeit not aggressively so. He too saw the euro-zone debt crisis on the inside as a Bank of Spain official.
His current job precludes commenting on a single institution’s policy. De Cos, who like Knot supported the creation of ECB emergency measures in recent years, delivered a speech on crises this month.
“If market dysfunction threatens financial stability or monetary transmission, central banks need to intervene,” he said. “But when debt is high and public financing needs are large, even a well-designed operation can be interpreted through a fiscal lens.”
Since either winning candidate may need to hold firm, at least initially, in the face of French fiscal profligacy, De Cos’s experience of preaching rectitude in Spain would prove useful. He also previously served on a euro-zone central bank working group on public finances, gleaning insight into regional policies.
Knot has credentials in that regard too, hailing from one of Europe’s more debt-prudent countries. He’s a former senior Finance Ministry official, a role with experience of fiscal policymaking and political tradeoffs.
Spain’s Opposition Leader Backs De Cos to Succeed Lagarde at ECBGermany Wants to Keep Schnabel’s Markets Portfolio at ECBMerz Will Meet Frontrunners for Lagarde Job as ECB Race Heats UpFour ECB Scenarios Sketch a Succession Plan for Post-Lagarde Era
Observers within central-banking circles describe differences between them in shades of grey rather than black or white. The bigger contrast is with Lagarde herself: the first woman and the first politician to serve as ECB president, and the only one who’d never run a central bank before.
Whatever happens, a politically fraught role awaits the next president. Earlier this month, Draghi said that public discussion in France centering on aid from the ECB has made the current situation uncomfortable.
“That if anything makes the interventions even more difficult,” he said. “The ECB, I assume, doesn’t want to be part of the political infighting in any specific country.”